A credit card dispute rarely becomes slow because one person cannot complete one task. It becomes slow because the case travels through multiple teams, systems, approvals and external deadlines. Each handoff creates an opportunity for waiting, incomplete evidence, duplicate entry or rework.
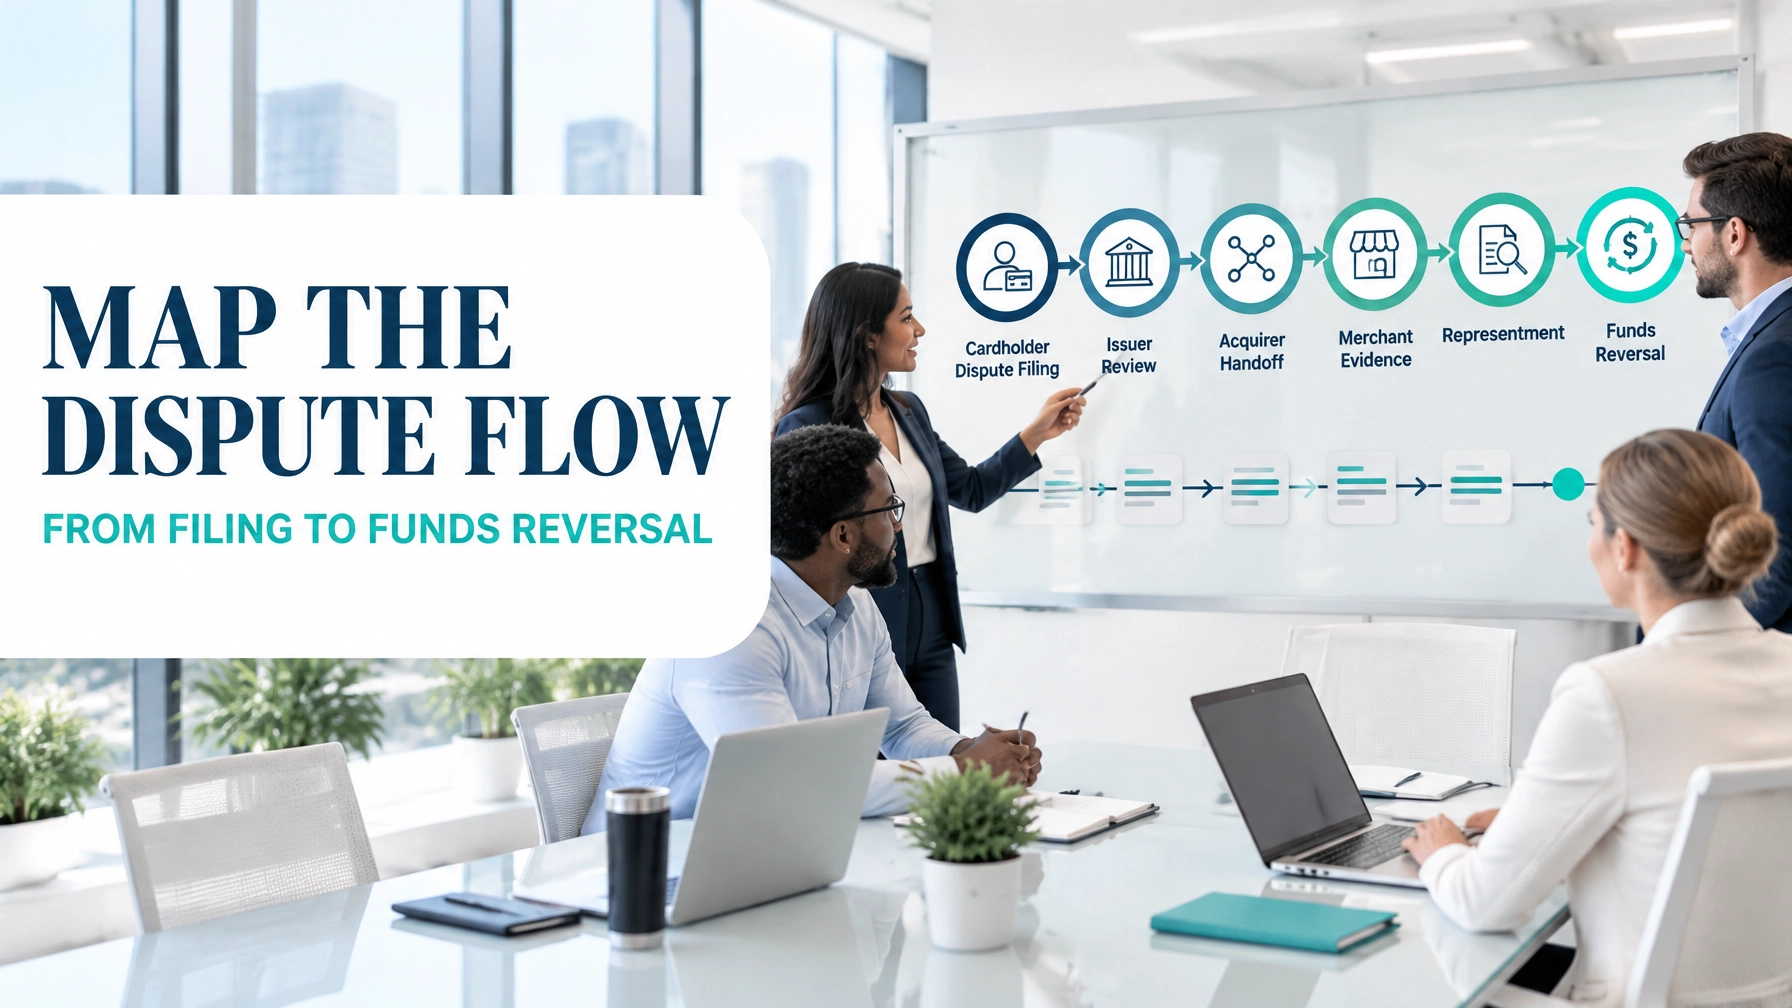
Value Stream Mapping (VSM) makes that hidden delay visible. In the realm of credit card dispute operations, the value stream includes the flow of customer information, transaction data, evidence, decisions and funds from the initial dispute filing through chargeback review, representment, possible arbitration and final funds reversal.
The objective is not simply to process cases faster. It is to create a reliable flow that protects the cardholder, gives merchants a fair opportunity to respond and enables issuers, acquirers and processors to meet network requirements consistently.
The timelines and rules vary by network, region, reason code and processor. Mastercard’s Chargebacks Made Simple Guide and Stripe’s Introduction to Payment Disputes illustrate the structured nature of the lifecycle. The numbers below are a realistic illustrative operating model, not a substitute for current network rules.
1. Select the Value Stream Scope
A useful VSM begins with a defined start point and end point. For this deep guide, the scope is:
- Start: Cardholder dispute received by the issuer
- Flow: Issuer validation, chargeback filing, acquirer routing, merchant evidence gathering, representment, issuer review and escalation
- End: Funds reversal to the merchant or final financial liability decision
- Volume: 120 cases per business day
- Monthly volume: Approximately 2,400 cases
- Case mix: Fraud, credit not processed, duplicate transaction, goods not received and service-not-as-described disputes
The Voice of the Customer includes timely provisional credit, clear communication and a fair review. The Voice of the Business includes reduced operating cost, controlled chargeback exposure and reliable deadline compliance. The Voice of the Process comes from case timestamps, queue sizes, evidence completeness, representment outcomes and escalation rates.
A strong future state must balance all three voices.
2. Current-State Map: Where the Processing Ping-Pong Begins
The current process uses separate queues for issuer review, acquirer notification, merchant evidence, quality assurance and representment. Cases are frequently returned because the reason code, transaction reference or supporting document is incomplete.

Current-State Worked Example
The operation has 480 available processing minutes per day and demand of 120 cases. Therefore:
Takt time = Available time ÷ Customer demand
Takt time = 480 minutes ÷ 120 cases = 4 minutes per case
This does not mean the full dispute can be completed in four minutes. It means each frontline intake position must complete, on average, one case every four minutes to match demand.
| Current-state step | Process time | Average waiting time | Main issue |
|---|---|---|---|
| Dispute intake and categorisation | 6 min | 0.2 days | Manual classification and duplicate entry |
| Issuer validation and provisional-credit decision | 18 min | 1.5 days | Approval queue and missing information |
| Chargeback creation and acquirer routing | 8 min | 0.5 days | Batch transfers between systems |
| Merchant evidence gathering | 42 min | 3.0 days | Evidence spread across CRM, order and delivery systems |
| Acquirer evidence QA | 15 min | 1.0 day | Rework caused by incomplete packets |
| Representment submission | 5 min | 0.5 days | Final approval and network formatting |
| Issuer review of representment | 20 min | 8.0 days | External review window and aged queue |
| Pre-arbitration assessment | 10 min | 2.0 days | Repeated case review and unclear ownership |
| Funds reversal and closure | 10 min | 0.5 days | Reconciliation and customer notification |
| Total | 134 min | 17.2 days | High waiting and handoff load |
Using an eight-hour workday, 17.2 waiting days equals 8,256 minutes. Total lead time is therefore approximately:
8,256 + 134 = 8,390 minutes, or 17.5 business days
The current activity ratio is:
Process Cycle Efficiency = Process time ÷ Lead time
134 ÷ 8,390 = 1.6%
Only about 1.6% of elapsed time is active processing. The remaining time is primarily waiting, queue accumulation, transfer, approval or rework.
With 2,400 open cases and throughput of approximately 137 cases per business day, the system carries about 17.5 days of WIP. This WIP is not physical inventory; it is partially completed case inventory, including disputes waiting for evidence, review, approval or reconciliation.
3. The Eight DOWNTIME Wastes in Dispute Resolution
The eight Lean wastes provide a practical diagnostic lens.
- Defects: Incorrect reason codes, missing transaction identifiers, unreadable evidence or an incorrect funds amount.
- Overproduction: Preparing full evidence packets for low-value cases that should be accepted or resolved through a standard rule.
- Waiting: Cases waiting for issuer review, merchant response, approval, arbitration or reconciliation.
- Non-utilised talent: Experienced analysts spending time searching for documents instead of analysing patterns and preventing repeat disputes.
- Transportation: Moving case information between email, spreadsheets, portals, CRM systems and network platforms.
- Inventory: Large queues of open disputes, unassigned cases and evidence packets awaiting review.
- Motion: Analysts switching between multiple screens and repeatedly searching for the same transaction history.
- Excess processing: Re-entering data, collecting irrelevant documents or requiring multiple approvals for standard, low-risk decisions.
The most important observation is that the bottleneck may not be the longest individual task. It may be the handoff between tasks. A 42-minute evidence activity can be efficient when information is complete, while a five-minute approval can create a three-day queue when decision rights are unclear.
4. Analyse the Root Causes
During the DMAIC Analyse phase, use a Pareto chart, queue ageing report, process timestamps, box plots and stratification by reason code. For example, a 30-day sample of 3,600 cases may show:
- 31% returned for incomplete evidence
- 24% delayed by missing transaction or delivery data
- 19% waiting for approval
- 14% incorrectly routed to the wrong team
- 12% delayed by external issuer or network review
A cause-and-effect analysis may identify three dominant causes:
- No single case owner across the end-to-end lifecycle
- Evidence requirements are not embedded at intake
- Approval rules are identical for routine and exceptional cases
The Y = f(x) principle is useful here: final resolution time, (Y), is a function of inputs such as reason-code accuracy, evidence completeness, queue size, approval policy and system availability. Controlling these critical inputs is more effective than asking analysts to work faster at the end of the process.
5. Future-State Design: Create Flow Around the Case
The future state should not remove controls that protect customers or satisfy network rules. It should remove avoidable movement and make necessary controls easier to complete correctly.

Recommended future-state principles include:
- Create a single digital case record with a unique transaction and dispute identifier.
- Apply reason-code decision trees at intake.
- Use automated evidence retrieval for receipts, authentication results, delivery data and customer communications.
- Replace routine sequential approvals with risk-based decision rights.
- Introduce an Andon-style visual alert for cases approaching deadline thresholds.
- Use standard evidence templates aligned with the dispute category.
- Route exceptions to specialists while allowing standard cases to flow through a dedicated lane.
- Display WIP limits by queue and assign one accountable case owner.
- Reconcile funds automatically when a chargeback is reversed or liability is accepted.
Future-State Worked Example
After redesign, the same operation achieves the following:
| Future-state measure | Current state | Future state |
|---|---|---|
| Total lead time | 17.5 business days | 6.2 business days |
| Active process time | 134 min | 102 min |
| Process Cycle Efficiency | 1.6% | 3.4% |
| Open WIP | 2,400 cases | 744 cases |
| Evidence returned for rework | 31% | 10% |
| Deadline compliance | 91% | 98.5% |
| Representment first-pass completeness | 62% | 90% |
| Arbitration escalation | 18% | 9% |
| Throughput | 137 cases/day | 150 cases/day |
The improvement comes from reducing waiting, not simply adding staff. Lead time falls because evidence is assembled earlier, standard cases receive faster decisions and exception work is separated from routine flow.
6. Kaizen Sequencing: Prioritise the Improvement Events

Sequence improvement work according to risk, impact and implementation effort.
1. Establish the case-control foundation
Priority: Highest
- Define one case identifier across issuer, acquirer and merchant records.
- Create a daily WIP and ageing dashboard.
- Set explicit ownership at every stage.
- Add deadline alerts at 50%, 75% and 90% of the available response window.
- Standardise minimum data fields at intake.
Target: Reduce unassigned cases by 80% and increase deadline compliance above 98%.
2. Build the evidence-at-source workflow
Priority: High
- Create reason-code-specific evidence checklists.
- Connect transaction, authentication, fulfilment and communication data.
- Use a completeness check before acquirer submission.
- Apply first-pass yield to representment packets.
Target: Increase first-pass completeness from 62% to 90% and reduce evidence rework by at least 60%.
3. Redesign approval and exception flow
Priority: High
- Separate routine, high-value and high-risk cases.
- Delegate standard approvals using documented thresholds.
- Escalate only cases requiring specialist judgement.
- Use daily bottleneck reviews for aged queues.
- Pilot the future state with one dispute category before scaling.
Target: Reduce approval waiting from one business day to less than two hours for standard cases.
4. Control and sustain the gains
Priority: Medium
Monitor:
- Lead time by reason code
- Process Cycle Efficiency
- WIP by queue
- First Pass Yield
- Rolled Throughput Yield from intake to closure
- Representment win rate
- Arbitration rate
- Deadline compliance
- Customer communication timeliness
This control plan links VSM to broader Lean Six Sigma governance. Agile practices can complement the rollout through short improvement sprints, rapid testing and frequent feedback from issuer, acquirer, merchant and compliance stakeholders.
Conclusion: Make the Value Stream Visible
Credit card dispute resolution is a service value stream governed by evidence, deadlines, funds movement and customer trust. Without a map, teams often optimise isolated steps while the overall case continues to wait between them.
A disciplined VSM reveals where information stops, where WIP accumulates, where approvals create bottlenecks and where defects trigger repeated handling. The future state then turns those observations into practical design choices: one case record, clearer ownership, earlier evidence capture, risk-based approvals and visible deadline control.
Build the capability to map, measure and improve complex financial processes. Enrol in Lean Six Sigma Training and pursue CSSC-accredited certification with Lean 6 Sigma Hub to lead measurable improvements across dispute operations and beyond.
Kaizen. Kai-Care. Kai-Done. ( Lean Six Sigma)