Commercial and corporate lending creates value when a suitable facility is approved, documented, available, and drawn by the customer. However, the customer experiences the entire journey, not individual departmental activities. A credit analyst may complete an assessment in hours, while the application waits days between handoffs, approval meetings, documentation reviews, and security registration.
Value Stream Mapping (VSM) makes this hidden delay visible. It connects customer demand, information flow, process time, queue time, rework, capacity, and control points in one end-to-end view. In the realm of lending origination, this is essential because the process is cross-functional, document-intensive, risk-sensitive, and often managed through multiple systems.
The fundamental purpose is not to remove prudent credit controls. It is to distinguish necessary risk management from avoidable delay. A well-designed stream protects credit quality while improving responsiveness, throughput, and the customer experience. General VSM principles are outlined in this Value Stream Mapping guide, while banking-specific applications are discussed in Value Stream Mapping for banking.
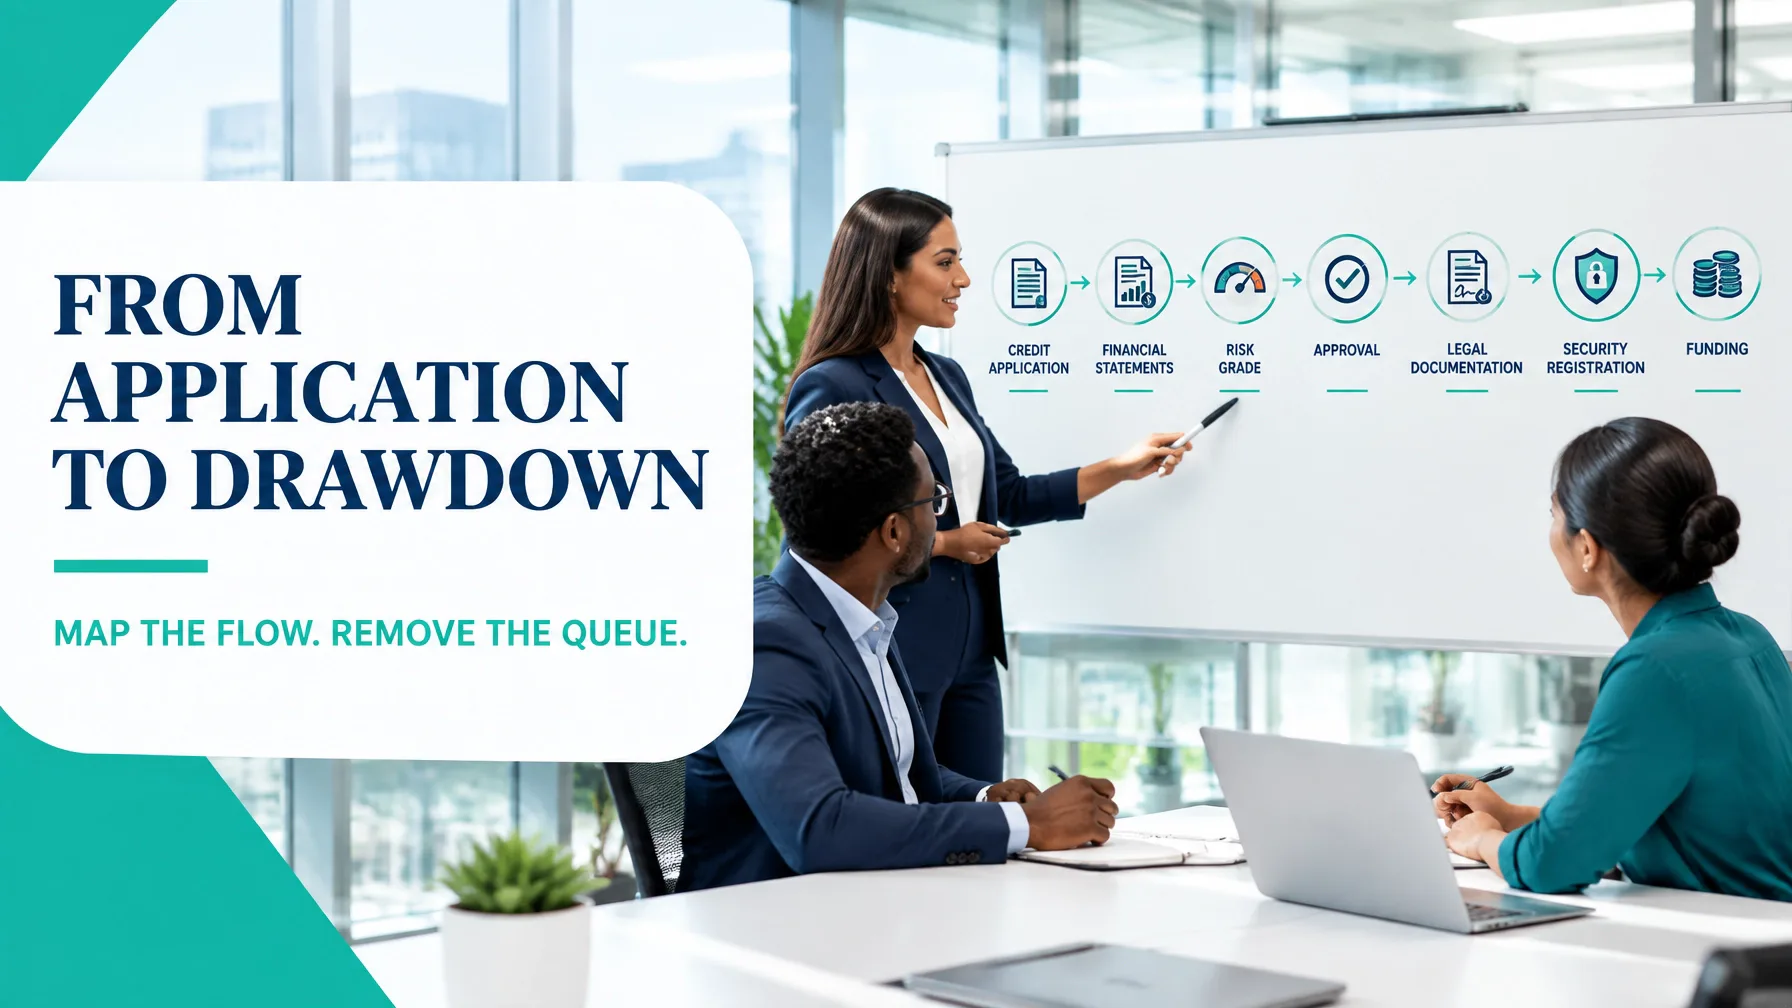
1. Scope the Lending Value Stream from Lodgement to Drawdown
Begin with a clear start and finish. For this analysis:
- Start: Complete commercial or corporate credit application lodged by the relationship team.
- Finish: Facility documented, security registered, conditions precedent satisfied, and first drawdown completed.
The scope includes:
- Application lodgement and initial triage
- Financial spreading and data validation
- Credit assessment and cash-flow analysis
- Risk grading and policy checks
- Credit committee or delegated authority approval
- Facility documentation and customer execution
- Security registration and conditions precedent
- Facility setup and drawdown
This scope excludes lead generation, ongoing portfolio monitoring, and post-drawdown servicing. Defining the boundary prevents the team from producing a broad process diagram that does not support actionable improvement. Lean Six Sigma practitioners can use the project scope boundary calculator to make the boundary explicit.
The map should include relationship managers, credit analysts, risk, legal, documentation, operations, technology, and customers. The Voice of the Customer may require speed and clarity; the Voice of the Business may prioritise risk-adjusted return and capacity; and the Voice of the Process comes from actual lead-time, quality, and queue data.
2. Current-State Map: Where the Credit Queue Forms

Consider a lending operation processing 96 applications per month, with an average facility size of $4.8 million. Seven credit analysts each have approximately 60 productive hours per month available for origination, giving total capacity of 420 hours.
The average analyst demand is 4.6 hours per application, or 441.6 hours per month before additional-information requests and rework. This creates a structural capacity gap of 21.6 hours, which appears operationally as an assessment queue. At the point of measurement, 21 files are awaiting credit assessment.
| Stage | Active work time | Average queue or wait |
|---|---|---|
| Lodgement and triage | 0.6 hours | 2.5 business days |
| Financial spreading | 1.8 hours | 5.0 business days |
| Credit assessment | 2.1 hours | 8.0 business days |
| Risk grading | 0.7 hours | 3.0 business days |
| Approval | 0.5 hours | 7.0 business days |
| Documentation | 0.6 hours | 5.0 business days |
| Security and drawdown | 0.1 hours | 3.5 business days |
| Total | 6.4 hours | 34.0 business days |
The map shows a critical distinction: 6.4 hours of value-added assessment and processing are surrounded by 34 business days of elapsed time. Assuming an eight-hour business day, process cycle efficiency is:
PCE = 6.4 ÷ (34 × 8) × 100 = 2.35%
The current-state findings are material:
- 38% of credit submissions are returned for additional information.
- Documentation requires an average of 2.7 rounds.
- First-pass approval rate is 61%.
- Approval cycle time averages 7.5 business days, including agenda waiting and clarification.
- Financial statements are often received in different formats, increasing spreading variation.
- Legal and operations teams frequently receive incomplete or changing instructions.
- Work in process accumulates before credit assessment and committee review.
A box plot of application-to-drawdown time would likely reveal a wide spread and several long-tail cases. Separating common-cause variation from special-cause variation is important: an overloaded committee may be a capacity issue, while one missing security document may be a specific defect.
3. Worked Example: Quantifying the Improvement Opportunity
The 96 monthly applications represent approximately $460.8 million in average requested facilities. If each application takes 34 business days to reach drawdown, customers wait a combined 3,264 application-days each month.
The map identifies three dominant constraints:
- Incomplete financial information creates rework before assessment.
- Serial approvals and committee batching create avoidable waiting.
- Documentation variation creates repeated legal and operational review.
The business case should therefore focus on flow rather than simply asking analysts to work faster. The relationship can be expressed as Y = f(x): drawdown lead time, the output Y, is influenced by inputs such as data completeness, approval routing, analyst capacity, documentation quality, and security readiness.
Use attribute data such as complete/incomplete, approved/referred, and drawdown-ready/not-ready alongside continuous measures such as hours, days, exposure size, and facility amount. A DMAIC Analyse Phase can then use Pareto charts, process stratification, a cause-and-effect diagram, and, where appropriate, ANOVA to test whether cycle-time means differ significantly by exposure tier, product, or approval pathway. A simple affinity diagram can organise workshop observations into meaningful categories such as data, decision rights, systems, documentation, and capacity.
4. The Eight Wastes in Commercial Lending Origination
Apply the DOWNTIME framework directly to the value stream:
- Defects: Incorrect financial spreads, missing covenant information, incomplete KYC, or documentation errors.
- Overproduction: Preparing full credit papers before confirming that the minimum data set is complete or the facility remains commercially viable.
- Waiting: Files sitting with analysts, risk teams, committees, legal counsel, or security registries.
- Non-utilised talent: Experienced credit professionals spending time chasing documents or correcting avoidable data-entry errors.
- Transportation: Moving information between email, spreadsheets, shared drives, workflow tools, and core banking platforms.
- Inventory: Excess work in process, including unassigned applications and partially completed credit submissions.
- Motion: Repeated searching for financial statements, approval history, templates, and security information.
- Extra-processing: Duplicated reviews, repeated data entry, unnecessary approval layers, and multiple documentation rounds.
The largest opportunity is usually Waiting, but the underlying cause may be a combination of defects, unclear decision rights, and uneven demand. Theory of Constraints provides a useful discipline: identify the current limiting factor, improve it, subordinate other activities to it, and then reassess throughput.
5. Future-State Design: Create Pull, Not More Batches

The future state should preserve risk discipline while creating a more deliberate flow.
Tier credit pathways by exposure and complexity
- Pathway A: Up to $1 million, standardised data, rules-based checks, delegated authority where risk criteria are met.
- Pathway B: $1 million to $10 million. Streamlined analyst review, standard risk grading, and scheduled delegated approval.
- Pathway C: Above $10 million or complex structures, dedicated deal team, early legal and risk involvement, and formal committee governance.
These thresholds must align with internal policy, portfolio risk appetite, and regulatory obligations. The objective is not to bypass control; it is to match the level of control to the risk and complexity of the facility.
Standardise the entry requirement
Create a minimum data set covering:
- Current financial statements and management accounts
- Borrower structure and ownership
- Facility purpose and requested amount
- Repayment source and cash-flow assumptions
- Security information
- Existing exposure and risk history
- Required covenants and conditions
An application should not enter the assessment queue until the minimum data set is validated. This reduces the current 38% rework rate at its source.
Replace batch movement with controlled pull
Use a visible workflow board showing:
- Current owner
- Current gate
- Age in gate
- Missing information
- Next decision
- Target completion date
Credit committee should pull complete cases from a ready queue rather than receive a large, inconsistent batch. Pre-approved documentation templates should be generated from standard facility data, reducing the average 2.7 documentation rounds.
An Andon-style visual signal can alert the team when a file exceeds its ageing limit, when a critical document is missing, or when a decision is blocked. Agile practices can complement this design through short improvement sprints, frequent feedback, and iterative testing of pathway rules.
6. Current State Versus Future State
| Metric | Current state | 90-day future-state target |
|---|---|---|
| Lodgement-to-drawdown lead time | 34 business days | 20 business days |
| Total active process time | 6.4 hours | 5.5 hours |
| Process cycle efficiency | 2.35% | 3.44% |
| Rework from incomplete submissions | 38% | 12% |
| First-pass approval rate | 61% | 82% |
| Documentation rounds | 2.7 | 1.3 |
| Cost to originate | $18,400 per facility | $12,600 per facility |
| Revenue recognition lag | 41 days | 24 days |
The future state improves throughput without assuming unlimited resources. It reduces queue time, clarifies decision rights, and increases first-pass yield. Control should include weekly ageing review, monthly process capability analysis, and an X-bar chart for average lead time alongside an R chart for variation.
7. A 90-Day Kaizen Sequence

Days 1–30: Measure and stabilise
Owners: Black Belt, Head of Credit Operations, Credit Analytics
Actions:
- Validate the current-state map using system timestamps.
- Define operational terms such as “complete,” “ready for approval,” and “drawdown-ready.”
- Establish baseline metrics for lead time, WIP, rework, yield, and ageing.
- Introduce a minimum data checklist.
Expected impact: Reduce avoidable intake rework from 38% to 25% and create reliable baseline data.
Days 31–60: Improve flow and decision rights
Owners: Credit Risk, Delegated Authority holders, Legal, Technology
Actions:
- Pilot tiered pathways for selected exposure bands.
- Move suitable decisions to delegated authority.
- Introduce pull-based committee scheduling.
- Deploy standard credit and documentation templates.
- Create visual ageing and escalation signals.
Expected impact: Reduce average lead time from 34 to 25 business days and documentation rounds from 2.7 to 1.8.
Days 61–90: Control and scale
Owners: Process Owner, Continuous Improvement Lead, Portfolio Governance
Actions:
- Confirm pilot results using stratified data.
- Use weekly control reviews for lead time and first-pass yield.
- Update standard work and training.
- Expand the model across products and regions.
- Review whether the bottleneck has moved to documentation, security, or drawdown.
Expected impact: Reach approximately 20 business days, 82% first-pass approval, and 12% rework, while maintaining credit policy compliance.
Build Capability Beyond One Lending Project
Value Stream Mapping turns a complex origination journey into a measurable management system. It shows where customers wait, where analysts lose capacity, where approval governance creates delay, and where standardisation can improve both speed and control.
Professionals who can connect customer requirements, process data, statistical analysis, and practical kaizen are equipped to lead improvements across lending, healthcare, logistics, finance, and IT. Lean 6 Sigma Hub offers online Lean Six Sigma Green Belt training, supported by practical simulations, worked examples, and end-to-end DMAIC project methods.
Enrol in Lean Six Sigma certification training and learn to map, measure, analyse, improve, and control high-value processes such as commercial lending origination.
Kaizen. Kai-Care. Kai-Done. Lean Six Sigma