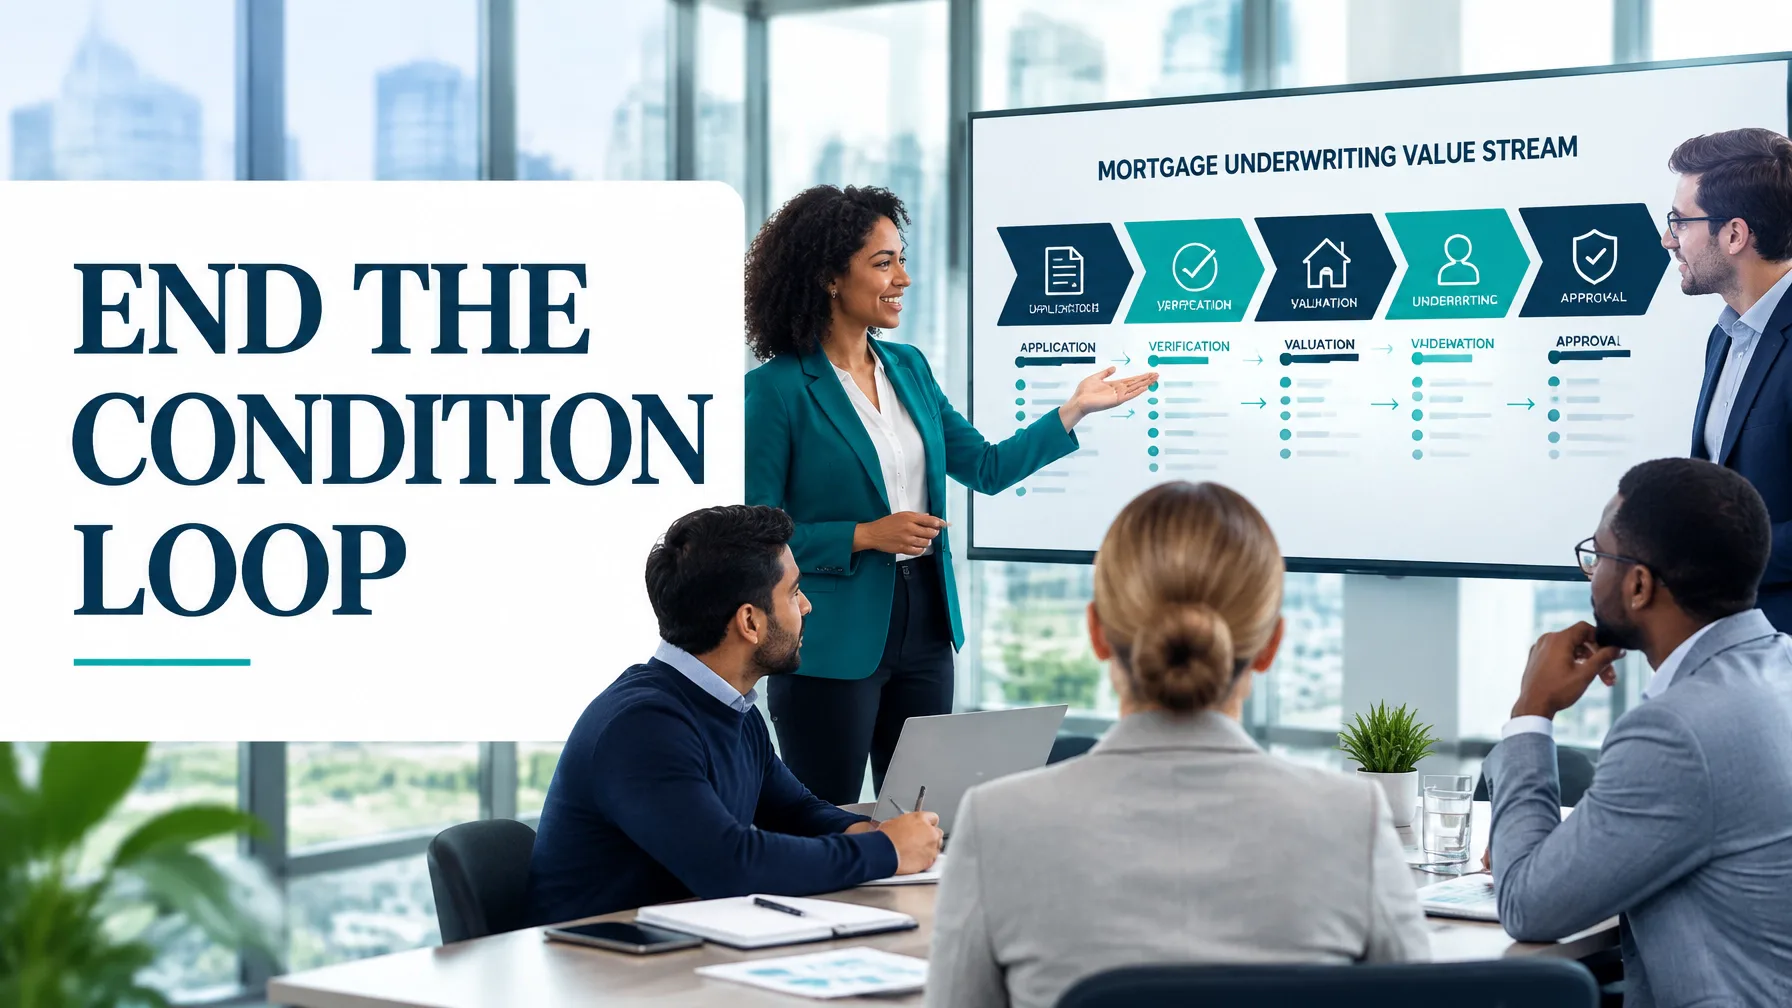
In the realm of mortgage origination, customers do not experience separate departments, software platforms, or underwriting queues. They experience one outcome: how long it takes to move from application lodged to formal approval.
That makes mortgage underwriting an ideal setting for value stream thinking. A value stream includes every activity, handoff, decision, document exchange, and waiting period required to deliver an outcome. Value Stream Mapping (VSM) makes the flow visible by separating customer-value work from delay, rework, and control activity.
For a borrower, value usually means a clear, reliable approval decision with minimal document repetition. For the business, value must also include responsible lending, credit risk control, compliance, and sustainable throughput. The challenge is to improve speed without weakening governance.
This worked example shows how a mortgage lender can map the process, quantify the condition loop, and design a future state using Lean Six Sigma principles. The figures are hypothetical but intentionally realistic.
1. Define the mortgage underwriting value stream
The Voice of the Customer (VOC) may require a fast, predictable decision. The Voice of the Business (VOB) may prioritise risk-adjusted growth, compliance, and lower cost per application. The Voice of the Process (VOP) reveals whether the current system consistently meets those expectations.
The fundamental purpose of VSM is not to make every activity faster. It is to improve the complete flow from customer need to customer outcome.
Scope selection
For this project, the map starts when:
A completed mortgage application is lodged in the loan origination system with the minimum required applicant and property data.
The map ends when:
Formal approval is issued and all approval conditions required before settlement are either cleared or explicitly documented.
This scope is appropriate because it captures the main underwriting experience while keeping settlement, post-approval documentation, and funding outside the primary project boundary. It also focuses directly on the condition loop: the repeated cycle of request, submission, review, clarification, and resubmission.
A separate project could later extend the map through formal approval to settlement.
2. Current-state map: where the time actually goes
The lender processes 1,200 applications per month:
- 720 broker-originated applications: 60%
- 480 branch-originated applications: 40%
- Average monthly demand: approximately 60 applications per business day
- Current fallout before formal approval: 12%
- Condition-related resubmission rate: 28%
- Current underwriting handoff first-time-right rate: 62%
- Verification touch time: 55 minutes per application
- Average VOE or employment-verification wait: 1.8 business days
- Average valuation wait: 3.0 business days
- Underwriting team allocation: 24 FTE
- 8 processors
- 6 underwriters
- 3 verification specialists
- 2 valuation coordinators
- 3 quality and operations staff
- 2 team leaders
The following current-state view separates touch time from elapsed waiting time.
| Process step | Touch time | Average wait | Underwriting observation |
|---|---|---|---|
| Application intake and file setup | 20 min | 0.5 days | Data is re-keyed from broker and branch channels |
| Completeness review | 35 min | 1.3 days | Missing documents are often discovered after handoff |
| Income, asset and employment verification | 55 min | 2.4 days | VOE creates the largest verification delay |
| Valuation order, receipt and review | 30 min | 3.0 days | Valuation is often triggered later than necessary |
| Underwriter queue and analysis | 45 min | 1.4 days | Work is released in batches |
| Initial decision and condition issue | 15 min | 0.4 days | Conditions vary in wording and specificity |
| Borrower or broker condition response | 40 min | 2.5 days | Multiple requests are sent at different times |
| Condition review and resubmission loop | 40 min | 1.8 days | 28% of files require at least one resubmission |
| Final QA and formal approval | 30 min | 0.8 days | Approval is delayed by a final sequential checkpoint |
The total is approximately 5.2 hours of touch time and 14.8 business days of lead time.
Process Cycle Efficiency
A practical PCE calculation is:
[
PCE = \frac{\text{Process time}}{\text{Total lead time}}
]
Using an eight-hour working day:
[
PCE = \frac{5.2}{14.8 \times 8} = 4.4%
]
That means more than 95% of elapsed time is not direct processing. It is queueing, waiting for information, waiting for capacity, or repeating work.
The condition loop is especially important. It is not simply a borrower problem. It is a system-design issue involving incomplete intake, inconsistent condition wording, unclear acceptance criteria, and sequential verification.

3. Worked analysis: identify the causes, not just the delays
A strong Measure and Analyse phase combines observation with data. Start with the average, but do not stop there. Use:
- Attribute data: complete/incomplete, approved/referred, pass/fail, and resubmitted/not resubmitted.
- Box plots: compare lead-time spread across broker, branch, property type, and verification method.
- Z-scores: identify unusually delayed applications across different product segments.
- ANOVA: test whether mean processing time differs significantly between broker and branch channels or between standard and complex properties.
- Bartlett’s Test: assess whether group variances are sufficiently comparable before relying on ANOVA assumptions.
- X-bar and R charts: monitor average approval time and the range of individual file times.
- Bias checks: verify that timestamps and manual status codes do not systematically distort the measured process.
- Y = f(x): treat approval lead time as the outcome, influenced by inputs such as document completeness, valuation type, verification route, queue size, and condition clarity.
The Analyse phase of DMAIC should distinguish common-cause variation from special-cause variation. A one-off employer delay may be special cause. A recurring 1.8-day VOE wait across every channel is a system-level cause.
The likely bottlenecks are:
- Completeness at intake
- Employment verification
- Valuation turnaround
- Batch release to underwriters
- Condition clarification and resubmission
- Sequential approval checkpoints
A useful capacity check is demand-based takt. At 60 applications per day and 450 productive intake minutes available daily:
[
Takt\ Time = \frac{450}{60} = 7.5\text{ minutes per application}
]
The intake process must therefore be designed to complete the initial data-validation task within approximately 7.5 minutes per application, supported by standard work and automated checks.
4. The eight DOWNTIME wastes in mortgage underwriting
The eight Lean wastes appear clearly in the current state:
- Defects: missing payslips, inconsistent income figures, incorrect property details, and incomplete declarations.
- Overproduction: duplicate document requests and reports generated before the file is ready for review.
- Waiting: VOE responses, valuation appointments, underwriter queues, and borrower clarification.
- Non-utilised talent: processors spending time chasing documents instead of analysing exceptions and improving the process.
- Transportation: moving documents between email, shared drives, broker portals, and the loan origination system.
- Inventory: work in process accumulating in verification and underwriting queues.
- Motion: repeated searching across systems and opening the same file multiple times.
- Extra-processing: duplicate QA checks, re-keying, repeated condition wording, and unnecessary approval signatures.
This analysis also highlights Andon and autonomation, or Jidoka opportunities. A digital Andon signal can alert a team leader when a file exceeds its verification service-level agreement. Jidoka principles can automatically stop an incomplete file from entering the underwriting queue rather than allowing defects to flow downstream.
Approval remains necessary for governance, but too many approval checkpoints create bottlenecks. The solution is not to remove control; it is to use risk-based approval tiers.
5. Future-state design: build flow and prevent the condition loop
The future state should introduce the following changes.
1. Create a single digital intake standard
Use one mandatory checklist across broker and branch channels, including the critical fields and documents required for a valid underwriting handoff. Introduce automated validation for missing fields, mismatched names, expired documents, and inconsistent income values.
Target: 95% complete and accurate intake.
2. Trigger work in parallel
Once minimum viable data is present, launch:
- Income and employment verification
- Asset verification
- Credit checks
- Valuation ordering
- Preliminary compliance checks
Do not wait for one activity to finish before starting the next unless risk rules require sequencing.
3. Segment standard and exception pathways
Standard applications should follow a simplified flow with defined service levels. Complex income, unusual property types, or policy exceptions should route to specialist underwriting.
This applies the Theory of Constraints: protect the constrained underwriting resource by preventing avoidable variation from entering the same queue.
4. Redesign condition management
Consolidate conditions into one structured request. Each condition should specify:
- The exact document or action required
- Why it is required
- The acceptable format
- The owner
- The due date
- The acceptance rule
Use a daily pull-based condition queue rather than releasing files in large batches.
5. Use visual control and clear ownership
Create a live dashboard showing:
- Files awaiting verification
- Files awaiting valuation
- Age of each queue
- Condition response age
- First-time-right rate
- Applications exceeding service-level targets
This gives teams an operational Andon system without turning the process into a collection of disconnected alerts.

6. Current versus future-state performance
| Metric | Current state | 90-day future-state target |
|---|---|---|
| Average lead time to formal approval | 14.8 business days | 5.0 business days |
| Process/touch time | 5.2 hours | 4.0 hours |
| PCE | 4.4% | 10.0% |
| First-time-right underwriting handoff | 62% | 88% |
| Condition resubmission rate | 28% | 10% |
| Approval rate from lodged applications | 62% | 67% |
| Fallout rate | 12% | 8% |
| Cost per application | $410 | $320 |
| Monthly formal approvals | 744 | 804 |
The business case is compelling: faster customer decisions, fewer repeated contacts, improved capacity, and an estimated $90 saving per application. At 1,200 applications per month, that represents approximately $108,000 in monthly operating opportunity, before considering improved broker satisfaction and additional lending capacity.
7. Ninety-day kaizen sequence

Wave 1: Days 1–30, Stabilise and measure
Owners: Process owner, Green Belt, operations analyst
Actions:
- Validate the current-state map using 50 broker and 50 branch files.
- Confirm timestamp definitions in the loan origination system.
- Publish one intake checklist.
- Baseline lead time, PCE, condition rate, fallout, and cost.
- Start a daily visual queue review.
Targets:
- Intake completeness: 85%
- Condition resubmission: 22%
- Lead time: 12 business days or less
Wave 2: Days 31–60, Improve flow
Owners: Underwriting manager, verification lead, technology owner
Actions:
- Trigger verification and valuation in parallel.
- Introduce VOE escalation rules at 24 and 48 hours.
- Create standard and exception lanes.
- Consolidate condition requests.
- Apply WIP limits to verification and underwriting queues.
Targets:
- VOE average wait: 1.8 days to 0.8 days
- Valuation wait: 3.0 days to 1.5 days
- First-time-right: 78%
- Lead time: 8 business days or less
Wave 3: Days 61–90, Control and sustain
Owners: Business process owner, Black Belt, risk and compliance leaders
Actions:
- Automate incomplete-file stops and service-level alerts.
- Establish a weekly X-bar and R review.
- Audit approval exceptions and condition quality.
- Document the new standard work.
- Create a control plan with owners, thresholds, and escalation rules.
Targets:
- Lead time: 5 business days
- PCE: 10%
- First-time-right: 88%
- Condition resubmission: 10%
- Fallout: 8%
Agile methods complement this work well. A cross-functional squad can test one intake rule, one verification trigger, or one condition template in a short iteration, review the data, and adjust without waiting for a large technology release. Agile supplies the flexible delivery rhythm; Lean Six Sigma supplies the measurement discipline and statistical validation.
Move from mapping to mastery
A mortgage underwriting VSM is more than a diagram. It is a structured way to connect customer value, risk governance, throughput, variation, cost, and capability. When the map exposes waiting and rework, leaders can invest in the causes rather than adding more pressure to already constrained teams.
If you want to lead improvements of this scale, develop the practical skills to define a business case, analyse process data, design future-state flow, and sustain measurable gains.
Start your Lean Six Sigma Green Belt or Black Belt online training with Lean 6 Sigma Hub, accredited by the Council for Six Sigma Certification (CSSC), and learn how to turn real operational problems into controlled improvement projects.
Kaizen. Kai-Care. Kai-Done. Lean Six Sigma