In life insurance claims, process delay is never merely an operational inconvenience. A beneficiary may be grieving, a trauma claimant may be managing a serious diagnosis, or an income protection claimant may be unable to work. Every queue, repeated request and unclear handoff is therefore felt emotionally as well as operationally.
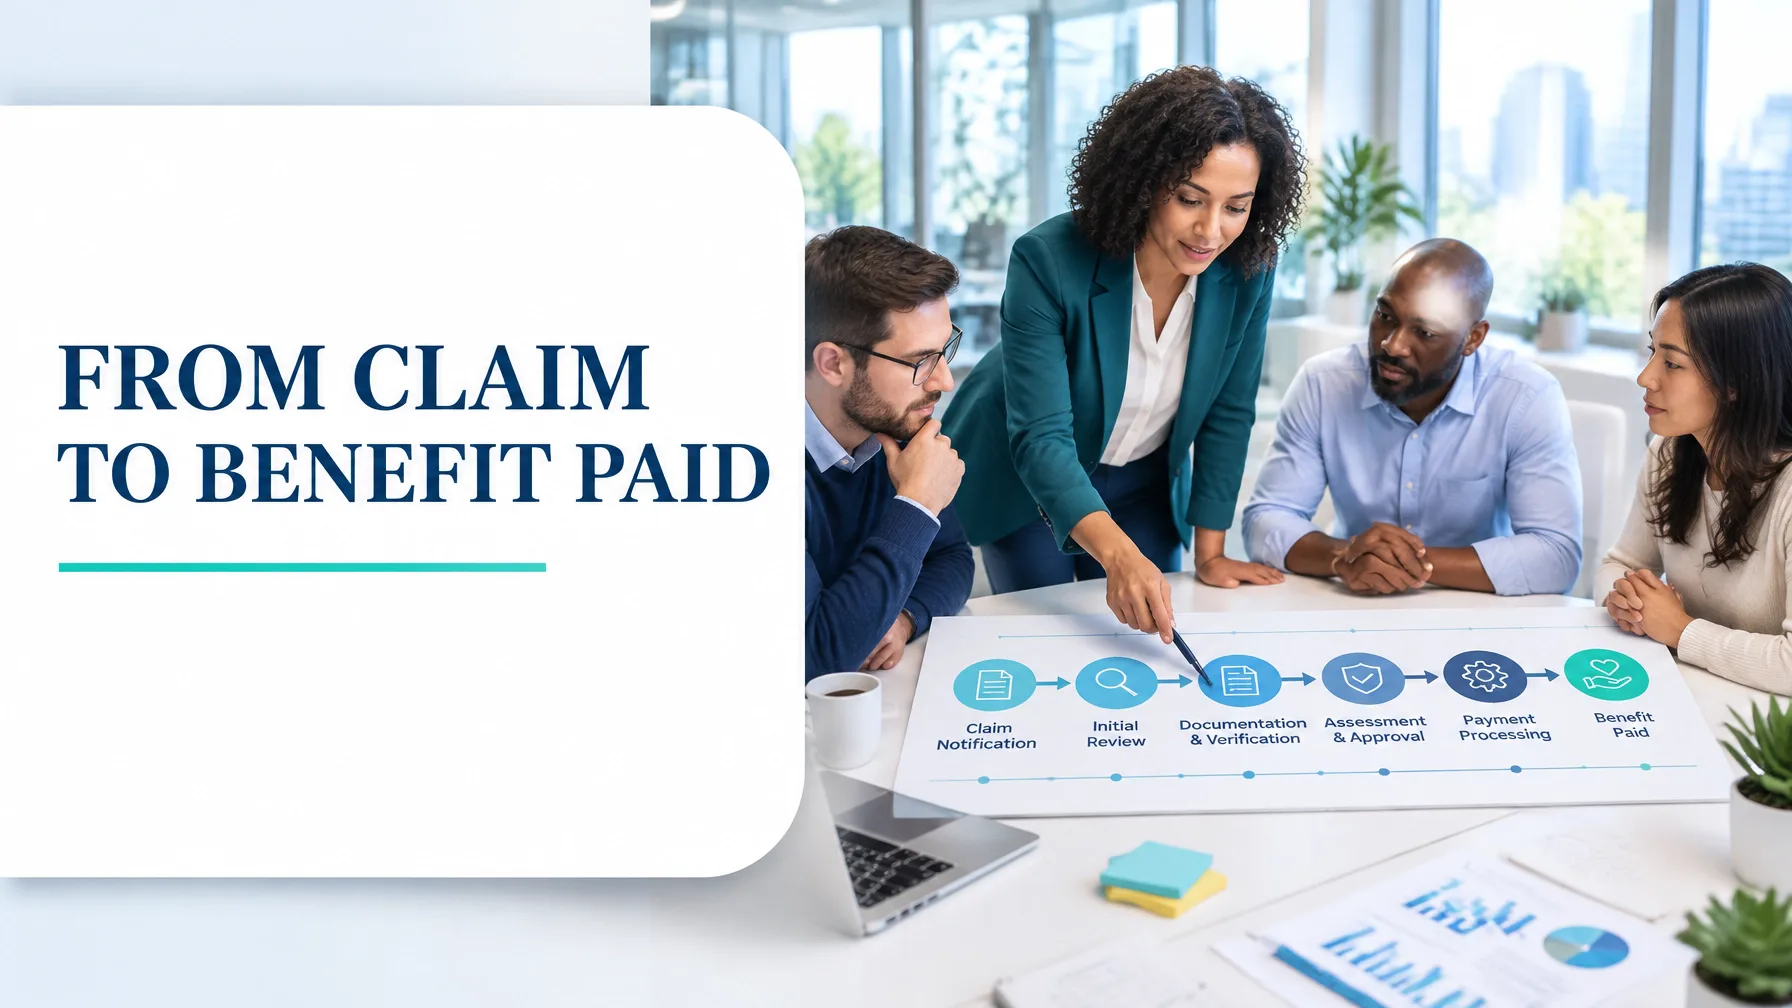
Value Stream Mapping (VSM) makes the complete claims journey visible. It connects customer experience, process flow, information movement, evidence requirements and operational performance in one view. Used within DMAIC, VSM helps teams distinguish genuine decision work from waiting, rework and administrative friction.
The objective is not to accelerate a poor decision. It is to create a claims process that is faster, clearer, controlled and evidence-based.
1. Select the Correct Claims Value Stream Boundary
For this guide, the mapping boundary begins at first notification of claim and ends when the benefit is paid and the claim is closed.
The in-scope flow includes:
- Claim notification and registration
- Verification of policy cover
- Initial reserve setting
- Medical evidence gathering
- Financial evidence gathering
- Employer or third-party report requests
- Assessment and decision preparation
- Peer review
- Benefit calculation
- Decision and approval
- Payment release
- Customer communication and closure
The map should show both process steps and queues between steps. It should also show the information exchanged with claimants, medical providers, employers, advisers, finance teams and external administrators.
Outside scope may include product design, underwriting before the claim is notified, premium collection, unrelated policy administration and litigation after formal closure. Fraud investigation or complex legal review should be included when it forms part of the selected claim pathway; otherwise, it should be mapped as a separate value stream.
A practical starting point is one product and claim type (for example, individual income protection claims) rather than attempting to map every life, trauma and disability process at once.
2. Current-State Map: Where the Evidence Chase Consumes Time
The following example uses a representative monthly data set for a life, trauma and income protection claims operation.
| Current-state measure | Observed result |
|---|---|
| New claims per month | 480 |
| Claims assessors | 32 |
| Average claim duration | 71 days |
| Open claim inventory | 1,120 claims |
| Notification to registration | 0.8 days |
| Cover verification cycle | 2.1 days |
| Medical evidence turnaround wait | 18 days |
| Third-party report wait | 16 days |
| Assessor touch time | 7.4 hours |
| Peer review queue | 4.6 days |
| Benefit calculation touch time | 1.2 hours |
| Payment release cycle | 2.3 days |
| Insufficient-evidence rework rate | 39% |
| Claims requiring a second evidence request | 46% |
| Total lead time | 71 days |
| Value-added time | 6.4 hours |
| Process Cycle Efficiency (PCE) | 0.38% |
The map tells an important story. A claim may require approximately 6.4 hours of value-added decision work, yet remain open for 71 days. Process Cycle Efficiency is calculated as:
[
\text{PCE}=\frac{\text{Value-added time}}{\text{Total lead time}}
]
Therefore:
[
\text{PCE}=\frac{6.4\text{ hours}}{71\times24\text{ hours}}=0.38%
]
This does not mean the claims team is inactive. It means most elapsed time is consumed by queues, external response times, handoffs and repeat evidence requests rather than customer-value-creating assessment work.
A current-state walkthrough should follow real claims from beginning to end. The team should validate timestamps, observe assessor work, identify every evidence request and record where a file returns to an earlier step.

3. Worked Example: Capacity, Claim Age and Reserve Exposure
Assume the operation receives 480 new claims per month, has 32 assessors, and operates for 20 working days per month with 7.5 available assessor hours per day.
Available monthly capacity is:
[
32\times20\times7.5=4,800\text{ assessor hours}
]
The available assessor capacity per new claim is:
[
\frac{4,800}{480}=10\text{ assessor hours per claim}
]
This is the operational takt allowance: the team has approximately 10 assessor-hours of available capacity for each incoming claim. It is not the same as calendar lead time. A claim can consume only 7.4 hours of assessor touch time and still remain open for 71 days because it is waiting for evidence or review.
The evidence loop is a significant contributor. Forty-six per cent of claims require a repeat evidence request, adding an average of 11 days each. The expected duration added across the total monthly cohort is:
[
480\times46%\times11=2,428.8\text{ claim-days}
]
On a monthly average basis, this is:
[
\frac{2,428.8}{480}=5.06\text{ days per claim}
]
If the repeat request is removed through better intake and evidence standards, average claim duration could theoretically fall from approximately 71 days to about 66 days before other improvements are included.
A one-day reduction in average claim age also has a measurable flow effect. With 480 claims arriving over 20 working days:
[
480\div20=24\text{ claims per working day}
]
Reducing average duration by one day releases approximately 24 open-claim positions from work in process. If the average outstanding reserve is $50,000 per claim, this represents an illustrative $1.2 million reduction in gross reserve tied up in open claim inventory:
[
24\times$50,000=$1,200,000
]
This does not remove the ultimate benefit liability. It indicates that claims move sooner from open inventory to a final outcome, improving visibility and potentially reducing the financial and operational exposure associated with ageing claims.
4. The Eight DOWNTIME Wastes in Claims
The eight wastes are highly visible in evidence-heavy claims operations:
- Defects: Incomplete claim forms, incorrect policy details, mis-set reserves and evidence that does not answer the decision question.
- Overproduction: Requesting medical or financial evidence that is not necessary for the specific claim decision.
- Waiting: Claims sitting with medical providers, employers, claimants, peer reviewers or approval queues.
- Non-utilised talent: Senior assessors spending time chasing reports, renaming files or correcting administrative errors.
- Transportation: Claims and information transferred between teams, inboxes, document systems and policy platforms.
- Inventory: Open claims accumulating in ageing buckets such as 0–30, 31–60, 61–90 and over 90 days.
- Motion: Assessors switching between multiple portals, spreadsheets, email threads and unconnected systems.
- Extra processing: Duplicate approvals, repeated quality checks and multi-layer reviews that do not change the decision quality.
A Pareto analysis of these categories can identify whether the largest opportunity lies in evidence completeness, provider turnaround, internal authority levels or system integration.
5. Future-State Design: Build a Decision-Ready Claim
The future-state map should reduce waiting without weakening controls. A practical design includes the following kaizen bursts:
- Front-load the evidence checklist: At notification, provide a tailored checklist based on claim type, policy conditions and the likely decision pathway.
- Create one claimant point of contact: Assign a named owner responsible for communication, evidence status and expectation setting.
- Define a decision-ready file: Establish the minimum evidence, verified policy information, reserve position and assessment notes required before a decision.
- Use tiered authority: Allow trained assessors to approve straightforward claims within defined limits, while reserving complex cases for senior review.
- Fast-track complete claims: Create a separate lane for claims that meet evidence, eligibility and authority criteria.
- Manage provider SLAs: Track medical and employer report requests by age, response commitment and escalation status.
- Introduce a visual ageing board: Display claim volume by age bucket, evidence status, owner and next action. Use a daily huddle to remove barriers.
The future state should also use pull-based work. A claim should move into assessment when its decision-ready conditions are met, rather than simply because it has reached the front of an administrative queue.

6. Current Versus Future Performance
The following targets are illustrative and should be validated through a pilot and control plan.
| Metric | Current state | 90-day future-state target |
|---|---|---|
| Average claim duration | 71 days | 45 days |
| Claims over 90 days | 18% | 5% |
| Insufficient-evidence rework | 39% | 15% |
| Repeat evidence requests | 46% | 12% |
| Cost per claim | $420 | $335 |
| Assessor touch time | 10.2 hours | 8.1 hours |
| PCE | 0.38% | 0.75% |
| Customer effort score* | 6.8/10 | 4.0/10 |
| Complaint rate | 7.2 per 100 claims | 3.5 per 100 claims |
*Lower customer effort is better.
The target state does not rely on a single technology intervention. It combines better evidence quality, clearer ownership, faster escalation, appropriate authority and visual management.
7. A 90-Day Kaizen Sequencing Plan
Days 1–30: Establish the baseline
Owners: Claims Operations Manager, Lean Six Sigma project lead, data analyst.
- Confirm the scope and claim segmentation.
- Map 20–30 real claims end-to-end.
- Validate timestamps against workflow and document systems.
- Create ageing buckets and evidence-rework Pareto charts.
- Define the decision-ready file standard.
- Measure customer effort and complaint drivers.
Use the Process Cycle Efficiency Calculator to standardise the baseline calculation.
Days 31–60: Pilot the improved flow
Owners: Claims Team Leader, Medical Evidence Lead, Compliance Manager, IT product owner.
- Launch the front-loaded checklist for one claim type.
- Assign a single claimant point of contact.
- Introduce provider response SLAs and escalation rules.
- Pilot tiered authority and a fast-track lane.
- Start daily ageing-board huddles.
- Audit decisions for quality, fairness and control adherence.
The pilot should compare at least 100 claims against the baseline, including lead time, repeat evidence requests, complaints and decision quality.
Days 61–90: Control and scale
Owners: Head of Claims, Finance Partner, Quality Manager, Continuous Improvement Lead.
- Confirm whether the pilot results are statistically and operationally credible.
- Update standard work, training and authority matrices.
- Add the future-state measures to the operational dashboard.
- Review cost per claim and reserve movement.
- Expand to trauma and income protection pathways where appropriate.
- Establish a monthly kaizen review for ageing, rework and customer effort.
A completed project storyboard can support governance and sustainment; the Lean Six Sigma Project Storyboard Toolkit provides a useful structure.
Build the Capability to Improve Claims Flow
Value Stream Mapping gives claims leaders a shared language for customer experience, evidence quality, operational capacity and financial performance. It turns the phrase “claims are taking too long” into measurable questions: Where is the queue? Why is evidence requested twice? Which approval adds value? What is the constraint?
Developing this capability requires more than learning individual Lean tools. It requires structured practice across Define, Measure, Analyse, Improve and Control.
Lean 6 Sigma Hub offers CSSC-accredited, self-paced online training from White Belt through Master Black Belt, with practical simulations, dummy data, worked examples and end-to-end DMAIC case studies. Choose the level that matches your role, build confidence with real improvement tools and learn how to convert claim-flow problems into sustainable performance gains.
Pursue Lean Six Sigma certification and build the capability to deliver faster, clearer and more compassionate claims outcomes.
Kaizen. Kai-Care. Kai-Done. Lean Six Sigma