In the realm of finance operations, revenue is not fully realised when an order is booked. It is realised when the customer receives an accurate invoice, pays according to agreed terms, and the payment is correctly applied to the right account.
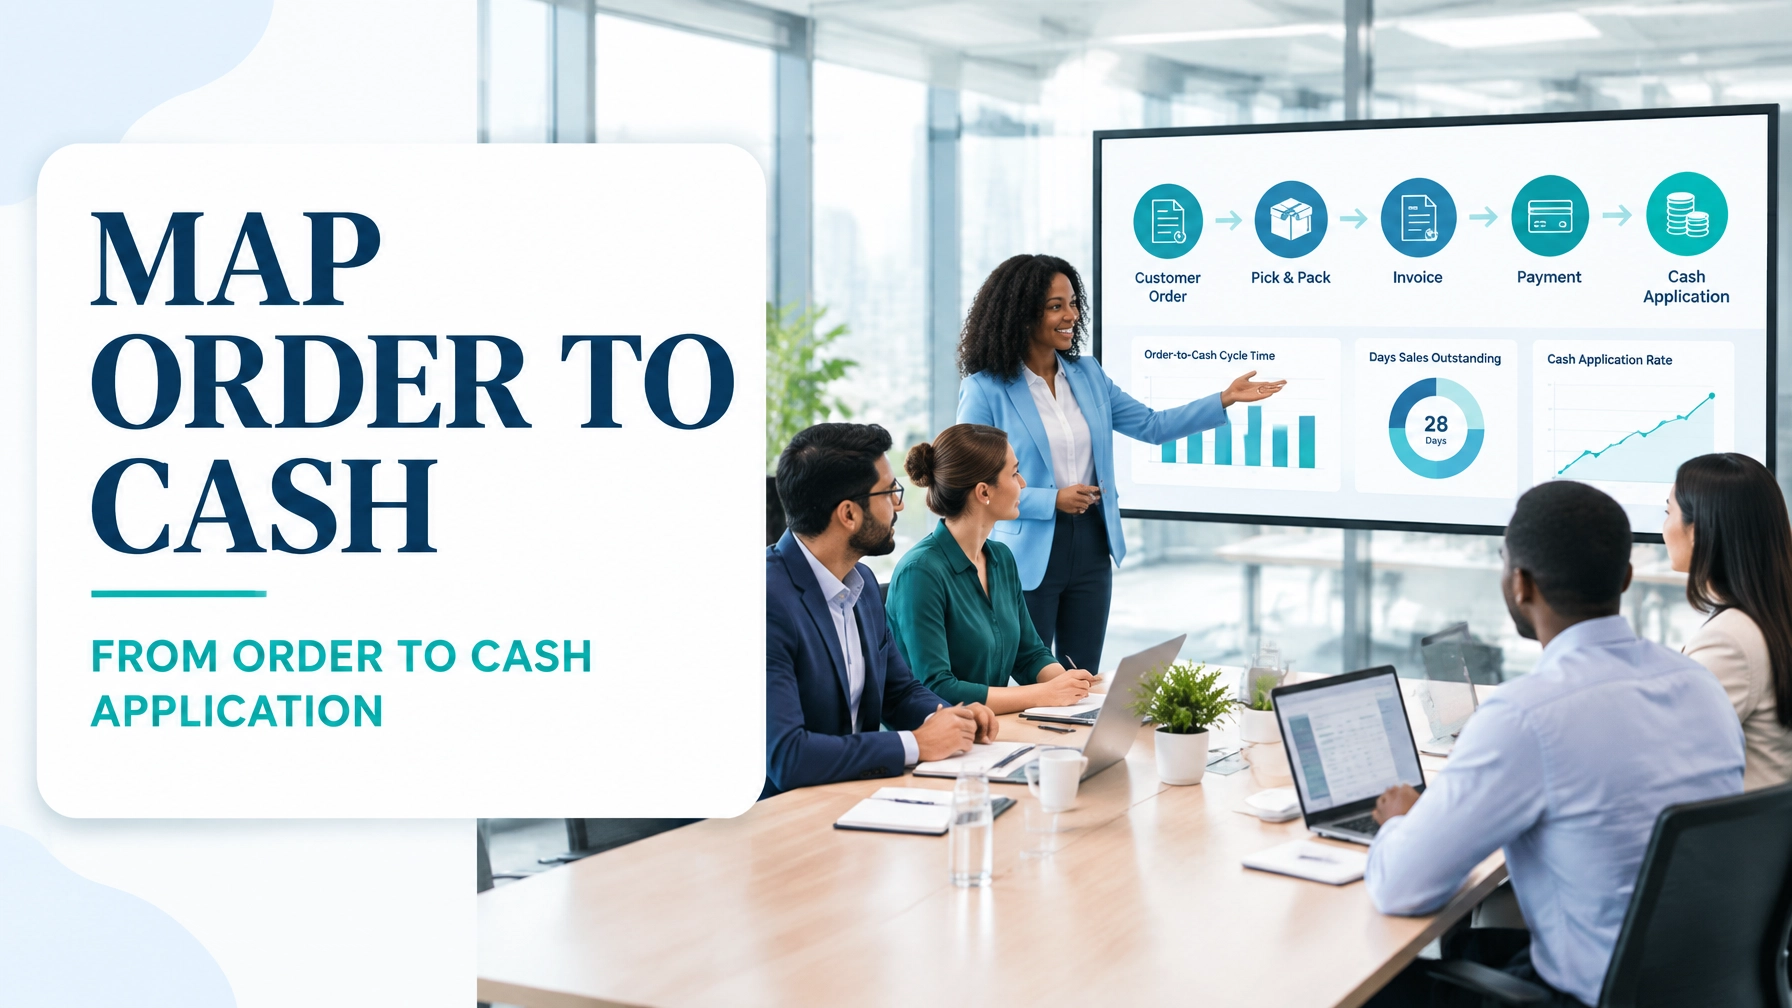
That makes order-to-cash (O2C) a finance value stream: not merely a sequence of accounting tasks. It connects order entry, credit, fulfilment, invoicing, payment, collections and cash application through both material flow and information flow.
A Value Stream Map exposes the difference between work that creates customer or business value and the waiting, rework, approval loops and defects that delay cash. This guide shows how to map the O2C process, quantify its performance and design a future state that reduces revenue leakage.
1. Define the O2C value stream and its critical requirements
Begin with a clear boundary:
- Start: Customer order accepted into the organisation’s system
- End: Customer payment received, correctly applied and the accounts receivable ledger updated
- Included: Order entry, credit check, fulfilment, invoicing, payment, collections and cash application
- Excluded: Sales opportunity development, product design and post-payment financial reporting
The team should include representatives from sales operations, credit, fulfilment, billing, accounts receivable, collections, cash application, IT and finance leadership.
Translate stakeholder expectations into measurable Critical to Quality (CTQ) requirements:
- Customer: Accurate invoices, clear payment instructions and fast dispute resolution
- Business: Lower Days Sales Outstanding (DSO), predictable cash flow and lower cost-to-serve
- Process: High first-pass invoice accuracy, rapid cash application and minimal exception work
These are the three essential voices:
- Voice of the Customer: “The invoice must be correct and easy to pay.”
- Voice of the Business: “Cash must be collected promptly without excessive administrative cost.”
- Voice of the Process: “Orders, billing events, payment references and ledger updates must flow without avoidable interruption.”
A strong business case should connect these CTQs to working capital. For example, reducing DSO by nine days on monthly billings of $12 million could release approximately $3.6 million in working capital, using a 30-day month assumption.
2. Build the current-state map with observed data
Do not map the process from a procedure manual alone. Follow representative transactions, review system timestamps and observe how teams manage exceptions. Capture:
- Touch time and waiting time
- Queue size and age
- Approval points
- Manual handoffs and system changes
- Invoice defects and disputes
- Payment references and matching outcomes
- Rework loops and escalation paths
The following worked example represents a finance organisation processing 15,000 invoices per month.
Current-state O2C data
| Process step | Value-added or touch time | Waiting or queue time | Current observation |
|---|---|---|---|
| Order entry | 4 minutes | 0.5 days | Manual rekeying for incomplete orders |
| Credit check | 6 minutes | 1.5 days | Approval queue for exceptions |
| Fulfilment confirmation | 180 minutes | 2.5 days | Delivery evidence arrives in batches |
| Invoice creation and dispatch | 3 minutes | 1.2 days | Billing runs once daily |
| Customer payment | : | 31.0 days | Payment timing affected by invoice accuracy and terms |
| Cash application | 4 minutes | 2.0 days | Remittance data often incomplete |
| Collections and disputes | 20 minutes | 4.3 days | Work prioritised through spreadsheets and email |
| Total | 217 minutes | 43.0 days | Baseline DSO: 43 days |
The total touch time is approximately 3.6 hours, compared with 43 calendar days of end-to-end lead time. The process cycle efficiency is therefore extremely low: most elapsed time is waiting, customer payment delay, rework or queueing rather than finance work that advances the transaction.
The baseline also shows:
- First-pass invoice accuracy: 68%
- Cash auto-match rate: 52%
- Unapplied or misapplied cash: 1,800 items per month
- Average dispute rate: 14%
- DSO: 43 days

3. Identify the eight wastes in order-to-cash
The eight DOWNTIME wastes appear just as clearly in an office or finance process as they do on a production floor.
- Defects: Incorrect prices, tax codes, customer details, purchase order references or payment allocations.
- Overproduction: Generating invoices before required fulfilment evidence is available, or producing duplicate reports and exception files.
- Waiting: Orders waiting for credit approval, invoices waiting for a billing run, and payments waiting for remittance details.
- Non-utilised talent: Skilled analysts spending hours rekeying data, searching email or correcting preventable invoice errors.
- Transportation: Moving files between ERP, CRM, bank portals, spreadsheets and shared drives.
- Inventory: Work in process accumulates as unbilled orders, disputed invoices, unapplied cash and aged collection cases.
- Motion: Employees switch between multiple systems to verify a single transaction.
- Extra-processing: Duplicate data entry, manual reconciliations, repeated approvals and reporting that does not influence a decision.
Look for the bottleneck, not simply the longest activity. In this example, the invoice accuracy problem creates downstream congestion. At 68% first-pass accuracy, roughly 4,800 invoices each month require correction, clarification or dispute handling. That increases collection effort and delays cash application.
An Analyse Phase team can validate the pattern with a Pareto chart of invoice defects, a box plot of payment lead times by customer segment, and a time-series view of unapplied cash. Where several customer or business groups are being compared, ANOVA can test whether their mean payment times differ significantly. Bartlett’s Test can assess whether variance assumptions are reasonable before applying ANOVA.
4. Design the future-state map around flow and prevention
The future state should not simply make each department faster in isolation. It should improve the complete flow from order to applied cash.
A practical future-state sequence is:
- Order validation at entry: Required customer, pricing, tax, purchase order and delivery fields are validated before the order is released.
- Rules-based credit check: Low-risk orders pass automatically; only exceptions move to a defined approval queue.
- Event-based fulfilment confirmation: The billing trigger is created when the required delivery or service event occurs.
- Same-day e-invoicing: Accurate invoices are sent through the customer’s preferred electronic channel with structured references.
- Standardised payment instructions: Bank details, invoice references and remittance requirements are clear and consistent.
- Cash application rules engine: Payments are matched using invoice number, customer account, amount, purchase order and remittance data.
- Exception management cell: People focus on ambiguous transactions rather than reviewing every payment manually.
- Segmented collections: Work is prioritised using value, risk, ageing, dispute status and customer behaviour.
This is where Autonomation, or Jidoka, becomes valuable. The system should detect a missing purchase order, invalid tax combination or ambiguous payment reference and stop the transaction for targeted intervention. Automation should not accelerate a defective process; it should expose the defect at the earliest practical point.
The governing relationship can be expressed as:
Y = f(x)
Cash applied on time = f(invoice accuracy, fulfilment confirmation, payment instructions, remittance quality, matching rules and collection cadence)
An Agile delivery approach complements Lean Six Sigma here. Instead of waiting for a large technology release, the team can test invoice validation, e-invoicing and matching rules in short iterations, using real exception data to refine the solution.

5. Compare the current and future state
The future-state targets below are illustrative and should be validated through a controlled pilot.
| Metric | Current state | Future-state target | Expected improvement |
|---|---|---|---|
| Monthly invoices | 15,000 | 15,000 | Volume maintained |
| First-pass invoice accuracy | 68% | 95% | +27 percentage points |
| Invoice dispute rate | 14% | 4% | 71% reduction |
| DSO | 43 days | 34 days | 9-day reduction |
| Cash auto-match rate | 52% | 92% | +40 percentage points |
| Unapplied cash items/month | 1,800 | 350 | 81% reduction |
| Cash application delay | 2.0 days | 0.5 day | 75% reduction |
| Manual approval volume | 100% of exceptions | 35% of orders | Targeted governance |
Formal approval checkpoints remain important for credit risk, pricing exceptions and financial control. However, approval can become a bottleneck when every transaction receives identical scrutiny. The future state uses risk-based rules so governance is preserved while routine flow improves.
6. Sequence four kaizen bursts
Do not launch every improvement simultaneously. Sequence the work so each intervention stabilises the next.

Kaizen 1: Stabilise master data and invoice quality
- Standardise customer, product, tax, pricing and payment fields
- Create invoice defect definitions
- Use a Pareto analysis to target the top three error causes
Expected impact: First-pass accuracy increases from 68% to approximately 80–85%; disputes fall by 30–40%.
Kaizen 2: Introduce event-based billing and e-invoicing
- Trigger invoices from confirmed fulfilment events
- Remove unnecessary batch delays
- Provide structured electronic invoice data
Expected impact: Billing wait time falls by approximately one day; invoice delivery becomes more predictable; DSO improves by 2–3 days.
Kaizen 3: Deploy rules-based cash application
- Define matching hierarchy and tolerance rules
- Standardise remittance requirements
- Route only genuine exceptions to analysts
Expected impact: Auto-match rate rises from 52% to 92%; unapplied cash falls by more than 80%; application delay reduces to half a day.
Kaizen 4: Segment collections and establish the control plan
- Prioritise accounts by value, risk and ageing
- Create standard work for dispute ownership and escalation
- Monitor DSO, first-pass yield, dispute rate and unapplied cash daily or weekly
Expected impact: A further 5–6 day DSO reduction becomes achievable, supporting the 34-day future-state target.
Use a Process Cycle Efficiency Calculator to quantify the baseline and confirm whether waiting time has genuinely reduced. The control plan should also define owners, thresholds, reaction rules and review frequency.
Turn O2C improvement into a professional capability
Value Stream Mapping provides the big-picture view. Lean Six Sigma provides the disciplined method for defining the problem, measuring the baseline, analysing root causes, improving the flow and controlling the gains.
If you want to lead projects like this, explore the Lean Six Sigma Practitioner Guide, then select the certification level aligned with your role:
- Yellow Belt for supporting improvement projects
- Green Belt for leading functional projects
- Black Belt for managing complex, cross-functional transformation
Build the capability to map the whole value stream, quantify the waste and deliver measurable cash-flow improvement: pursue Lean Six Sigma certification with Lean 6 Sigma Hub.
Kaizen. Kai-Care. Kai-Done. ( Lean Six Sigma)